According to The Wall Street Journal, agentic trading in the US is evolving from an experiment into a standard product: private investors are connecting AI agents Claude and Codex to brokerage accounts, where the agents independently buy and sell stocks and options based on text instructions, while skeptics and researchers note that there is currently no public evidence of sustained profitability for such systems.
What happened
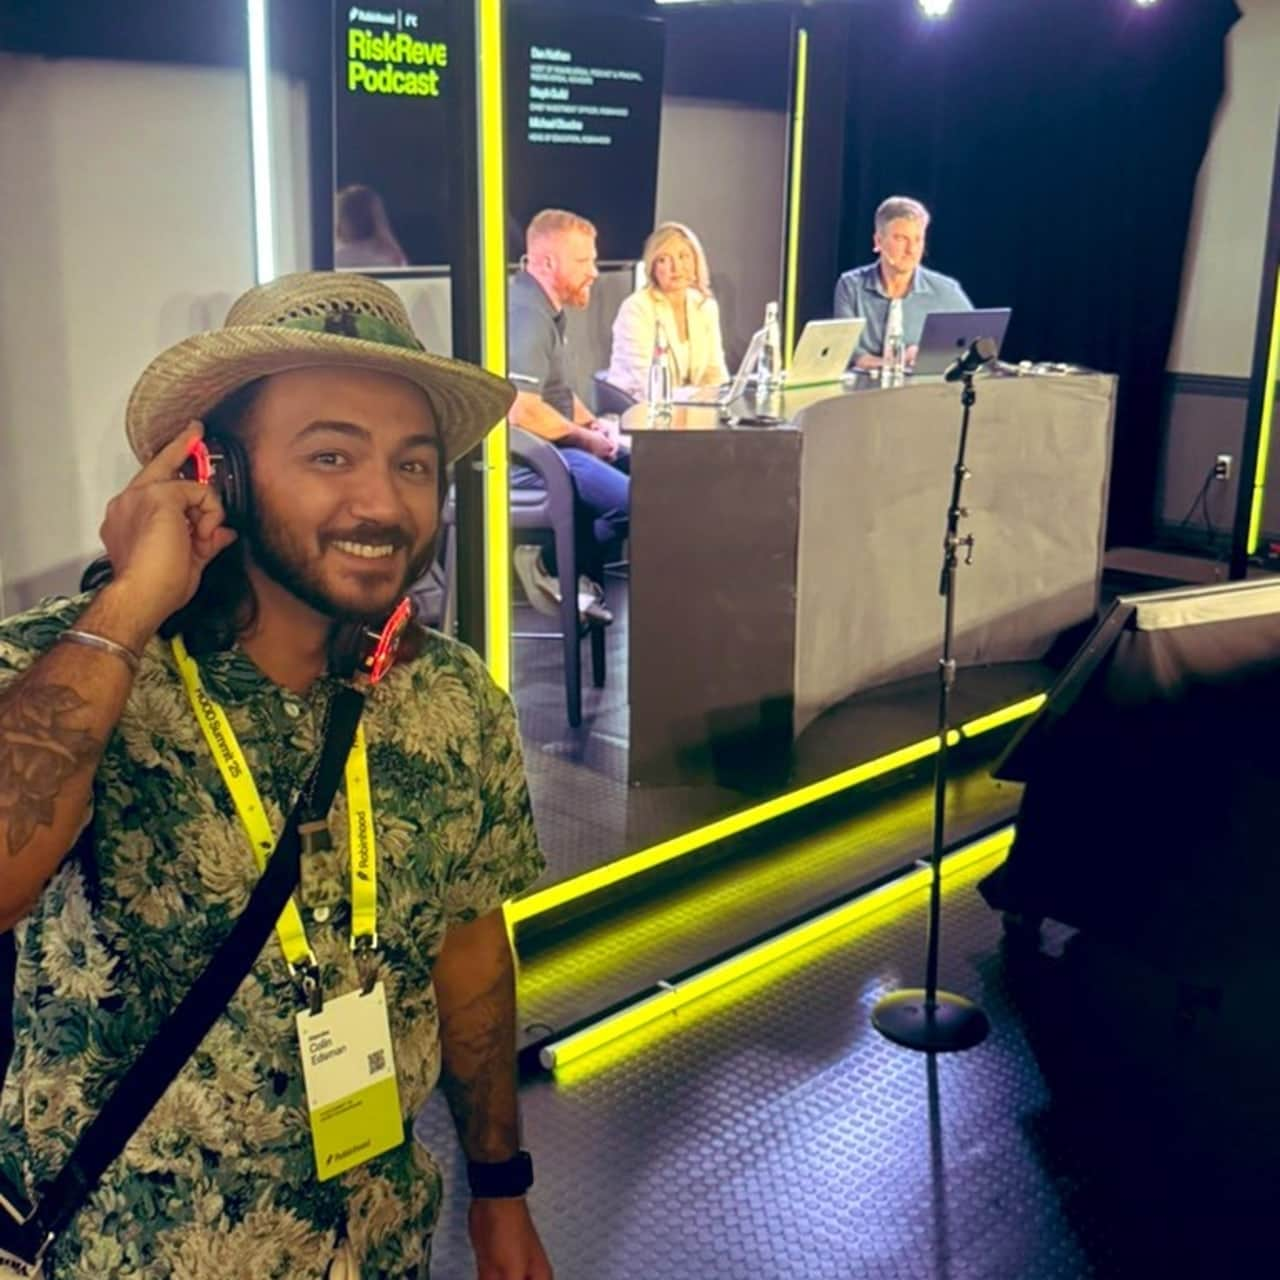
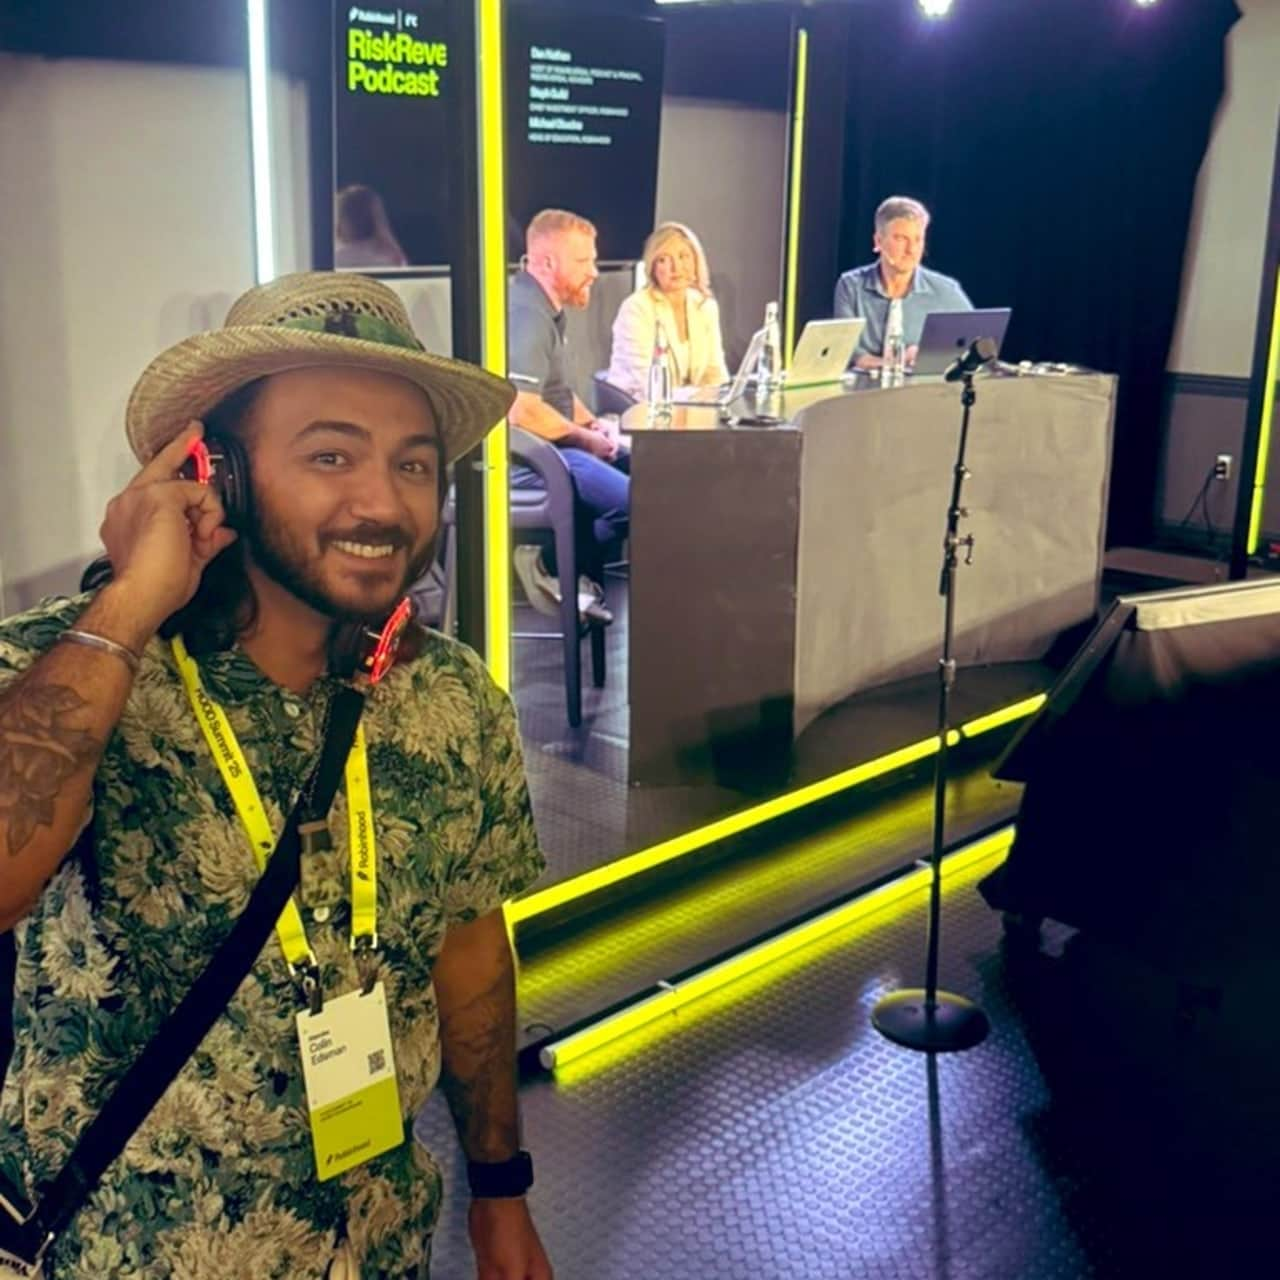
In a September 6, 2026, article by Hannah Erin Lang, The Wall Street Journal provides the first everyday examples. Hairdresser and father Collin Edsman runs three named Claude agents on Robinhood: Alex scans the market, Sarah checks open positions daily, and Elena prepares a weekly report. 19-year-old Dean Arens reports that a Codex agent on the Public platform grew his account from $3,000 to $8,000 in a few months, and a trade on two Micron Technology options contracts yielded over 500% profit. Moomoo launched agentic trading in April 2026, and the company's US CEO Neil McDonald expects that by the end of the year, about 20% of the platform's trading volume will be executed by agents.
Context
From a technological standpoint, the combination is not new: Claude and Codex are already existing large language models, and the new element is the agentic layer that makes trading decisions based on text instructions and passes them for execution via brokerage APIs. The article draws a parallel with the 2007 "quant meltdown" and explains it by the fact that if mass agents choose the same signals from the same public data, they form correlated positions and can amplify market volatility. The only research source cited by The Wall Street Journal is an NBER working paper: according to its data, AI strategies tend to build concentrated portfolios of overvalued, high-media-attention stocks and on average do not outperform passive benchmarks.
Why this matters for the industry
Brokers Robinhood, Webull, Moomoo, and Public are turning AI agents into a new execution layer and a customer acquisition channel: retail investors are getting a quantum toolkit for the first time — data screening, signal scoring, and trade execution — without their own team of analysts. Moomoo's stated 20% agentic volume by the end of 2026 will be the first major public snapshot of real LLM agentic trading results, before which evidence was limited to self-reports from individual traders. For developers, this is a ready-made production environment where agentic workflows can be debugged in a domain with real money, and they get distribution on the broker side without building their own brokerage business.
Why this matters for users
Agentic trading can be tried right now: Robinhood isolates AI portfolios in a separate account and sends notifications about each trade, Moomoo, Webull, and Public have also integrated Claude and Codex into their platforms, and management is reduced to simple text instructions. All results cited in the article are trader self-reports and cannot be considered evidence of sustained profitability. Former quant trader Irene Aldridge, quoted in the material, describes the situation as "a real breakthrough, but on your own risk." A practical approach is to experiment only with a separate account and with amounts that can be lost, understanding that there is no public evidence of agents outperforming passive strategies.
What is still unknown / limitations
All figures from the article — Dean Arens' $8,000 and over 500% on Micron Technology options — are one-off self-reports without audit, backtests, out-of-sample testing, accounting for transaction costs, and drawdowns. Moomoo's forecast of about 20% agentic volume is a stated goal, not a confirmed fact, and the risk-limiting and operation-cancellation mechanisms in agentic portfolios are not described in the material. A direct link to the NBER working paper is absent from the materials, so its conclusions rely on a retelling in The Wall Street Journal.
Sources
- The Wall Street Journal — The AI Shift: Turning Everyday Investors Into Mini Quant Funds
- National Revealed — syndicated version of The Wall Street Journal article
Author
Look at AI, editorial team